Template 14
ASC 842 Lease Workpaper for Lessees
Supports lessee lease balances and the lease note: lease-by-lease rollforwards of right-of-use assets and lease liabilities, the current / noncurrent split, the maturity analysis with imputed interest, weighted-average remaining term and discount rate, lease cost and supplemental cash flows.
Tab structure
- Instructions
- Setup (with workpaper header and the present-value check tolerance)
- Summary & Tie-out
- Lease Register – classification, dates, discount rate, ROU and liability rollforwards, current portion, remaining term; totals by class, weighted averages and balance sheet ties
- Maturity Analysis – years 1–5 and thereafter per lease, imputed interest, a rough present-value check, and the disclosure table by class
- Lease Cost & Cash Flows – cost components, supplemental cash flow and non-cash information, tied to the register
- Judgments
- Completeness & Controls
- Open Items
- Sign-offs & Refs
- Tickmarks
- Lists
Built on the common workpaper framework – see the templates overview.
Key checks and flags
- Operating and finance ROU assets and liabilities (current and noncurrent) tie to the balance sheet
- Weighted-average remaining term weighted by the liability; discount rate weighted by remaining payments (ASC 842-20-55-11, 55-12)
- Undiscounted payments below the liability read Investigate; a mid-year present-value estimate flags rows for review
- Finance amortization, interest, payments and new ROU assets agree to the register
- Missing classification, rate or end date, expired leases with a balance, and current portion above the liability are flagged
Who uses it
Lease accountants and SEC reporting preparing the lease note and lease balances.
Primary sources
Previews
Rendered from the actual workbook with illustrative sample data ("Example Company, Inc.", period end December 31, 2026). Scroll sideways on small screens.
Lease Register
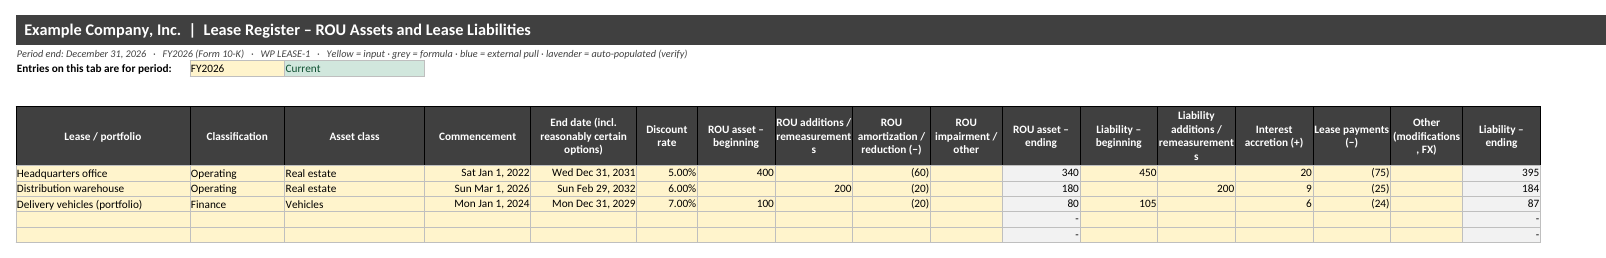
Lease Register tab: ROU asset and liability rollforwards by lease.
Maturity Analysis
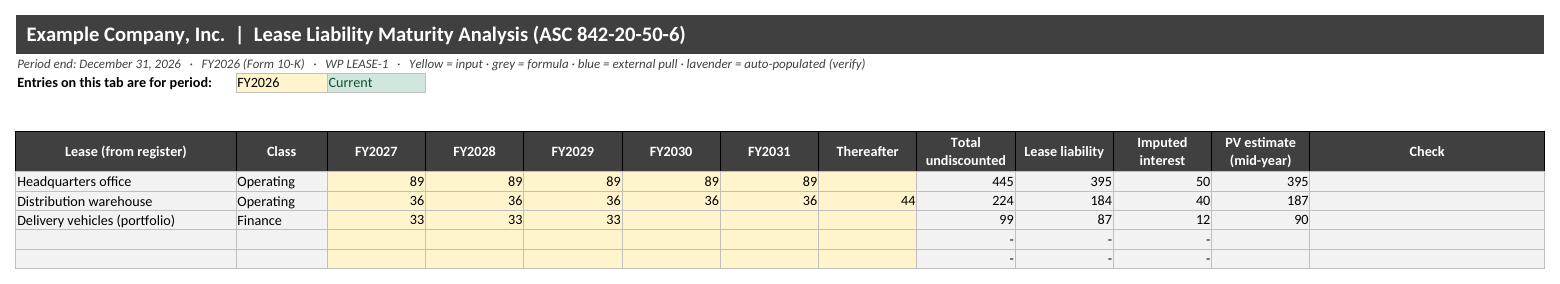
Maturity Analysis tab: payments by year, imputed interest and the present-value check.