Template 07
Cash Flow Statement Workpaper
Builds and proves the indirect-method statement of cash flows: every balance-sheet change is explained by cash-flow lines or documented non-cash items, and cash plus restricted cash ties to the balance sheet.
Tab structure
- Instructions
- Setup
- Summary & Tie-out
- Balance Sheet – each caption mapped to a cash-flow category: change, expected cash effect, explained by cash-flow lines, non-cash / other, unexplained, result
- Cash Flow – each line as presented, mapped to a balance-sheet caption, with source and tickmark
- Supplemental – interest paid, income taxes paid with the federal / state / foreign split and 5% jurisdictions (ASU 2023-09), non-cash investing and financing activities, cash + restricted cash reconciliation
- Judgments
- Completeness & Controls
- Open Items
- Sign-offs & Refs
- Tickmarks
- Lists
Built on the common workpaper framework – see the templates overview.
Key checks and flags
- Unexplained balance-sheet changes flagged line by line
- Cash, cash equivalents and restricted cash reconciled to the balance sheet (ASC 230)
- Income taxes paid: federal + state + foreign must equal the total
- Non-cash amounts without an explanation and cash-flow lines without a section are flagged
- YTD current and comparative periods for a 10-Q (S-X 10-01)
- Completeness prompts: non-cash items excluded, FX effect not a plug, gross vs net borrowings, classification consistency
Who uses it
Preparer and reviewer of the cash flow statement and MD&A liquidity section.
Primary sources
Previews
Rendered from the actual workbook with illustrative sample data ("Example Company, Inc.", period end December 31, 2026). Scroll sideways on small screens.
Balance Sheet
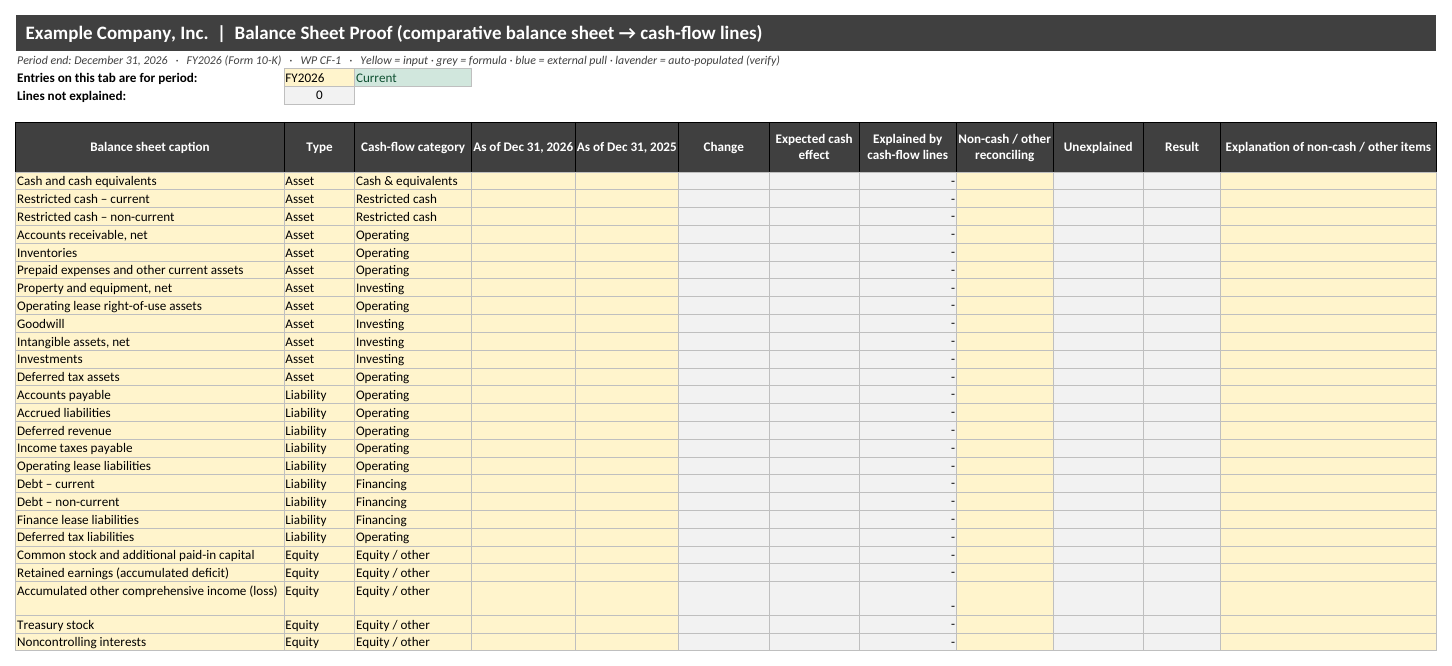
Balance Sheet tab: every change must be explained.
Supplemental
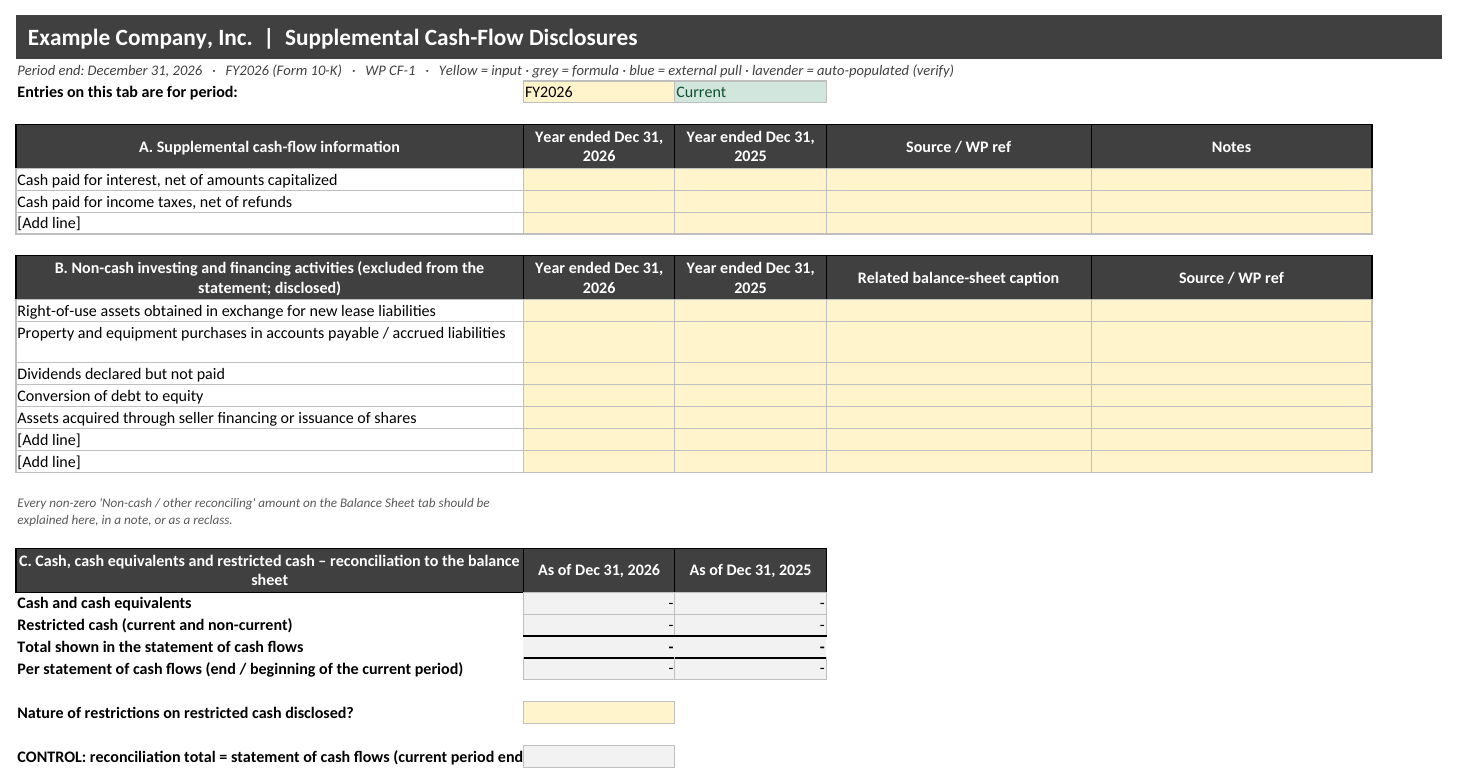
Supplemental tab: non-cash activities and restricted cash reconciliation.